Disclaimer: This article is for general information only. It isn’t financial, legal, tax or mental health advice, and we aren’t financial advisors, attorneys, tax professionals or health care providers. Credit card terms, lender offers and debt collection laws change, and many of them differ by state. Check the details with the issuer or lender, and consider talking to a nonprofit credit counselor or a licensed attorney about your own situation.
Getting out of credit card debt is two problems at once. One is math: how much you owe, what it costs and how fast you can pay it. The other is behavior: staying motivated for months or years, handling setbacks, and not building the balance back up.
Our other guides cover the math, including a step-by-step payoff plan and a comparison of snowball vs. avalanche. This one is about the second problem: how to keep going.
The short version
- Getting out of debt is slow at first, because a lot of each payment goes to interest. That’s normal, and it isn’t a sign that you’re failing.
- Write your debts down in one place, set a goal with a date, and break it into milestones.
- Automate what you can, so progress doesn’t depend on willpower.
- Make overspending harder and keep a small cushion for surprises.
- Plan for slip-ups, and get help early if you’re struggling.
Why it’s hard, and why that isn’t a character flaw
Interest makes the early months feel slow. On a $6,610 balance at 22.15%, which is the average per borrower for TransUnion’s Q2 2026 figures and the Fed’s average rate on accounts charged interest, the first month’s interest is about $122, according to our calculation. A big part of your first payments goes there, so the balance moves less than you’d hope.
The way people think about debt makes it harder too. Researchers including Dan Ariely ran experiments in which participants managed several debts in a game with real incentives. In four experiments, participants consistently paid off small debts first even when larger debts carried higher rates. In one experiment described by the researchers, only 5 of 162 participants allocated their money in a way that was close to optimal. In other words, almost everyone has a hard time with this, and wanting to see accounts close is a normal reaction.
And you’re not alone. The American Psychological Association’s Stress in America surveys have repeatedly found money to be a top source of stress for Americans.
Step 1: Look at all of it, without judging yourself
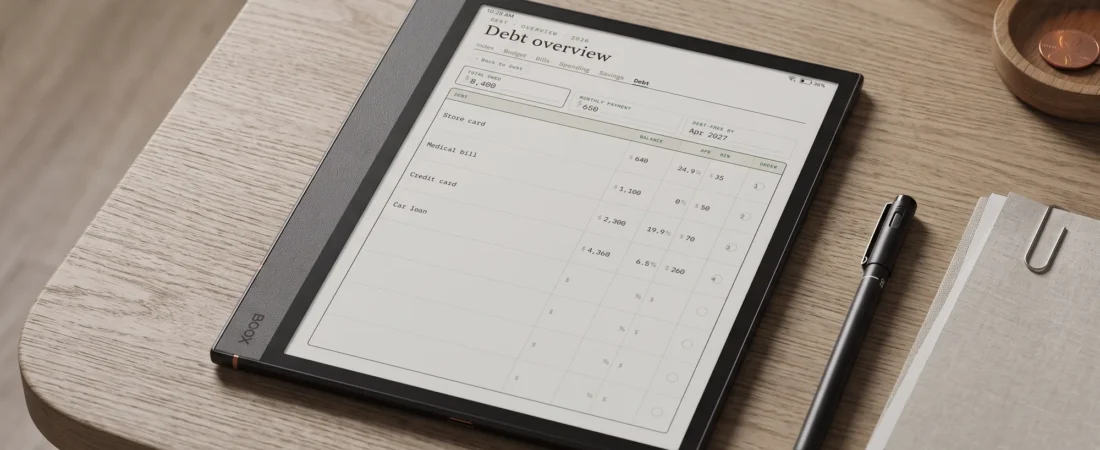
Avoiding statements is common, and it makes things worse. Set aside an hour with a cup of coffee and your statements. Write down each card’s balance, APR and minimum payment on one page.
The CFPB offers free tools for this. Its debt worksheet helps you list your debts and plan how to pay them off, and its spending tracker helps you see where your money goes.
Your statement also has a box that shows how long it would take to pay off the balance with minimum payments only, and how much to pay each month to clear it in 36 months. The CFPB explains how to read it.
Step 2: Set a goal with a date, and break it up
“Get out of debt” is too big to act on. Make it concrete:
- Pick a payoff date, or a monthly amount. Our credit card payoff calculator shows how long a given payment takes, and what payment you’d need for a deadline.
- Divide it into milestones. The first card gone, a third of the total paid, halfway.
- Write down the date of each milestone.
Here’s what milestones look like in the example from our payoff plan: three cards totaling $9,400, with $450 a month and the highest rate first. The first card is gone in month 9, the second in month 19 and the last in month 27. That’s our own calculation, with fixed rates and no new purchases.
Research on how people repay debt suggests why this helps. A study by Keri Kettle and colleagues in the Journal of Consumer Research found, as summarized by others, that concentrating repayments on one account boosts motivation to get out of debt, because people judge their progress by the biggest drop they see in any one account. It’s mostly based on experiments, so it’s a clue about behavior rather than a promise.
Step 3: Make it automatic
Willpower runs out. Systems don’t.
- Automate at least the minimum payment on every card so you’re never late.
- Schedule your extra payment for the day after payday.
- Send it to the right card. Our article on snowball vs. avalanche helps you choose an order, and it matters less than sticking with it.
Step 4: Make overspending harder
You don’t need to go without everything. You do need some friction between you and a new charge:
- Remove saved card numbers from your phone, browser and shopping apps.
- Use debit or cash for everyday spending for now.
- Unsubscribe from marketing emails and promotions that tempt you.
- Add a waiting period for non-essential purchases, such as a day or a week.
Step 5: Keep a small cushion
A surprise bill is what sends many people back to the card. The Federal Reserve’s household survey found that 63% of adults would cover a $400 emergency using cash or its equivalent, so 37% would not, and 12% said they couldn’t pay it by any means.
If you have no cushion, even a few hundred dollars set aside can keep one repair bill from becoming another balance. It may feel slower to pay down debt while saving a little, but it protects the progress you’ve made.
Step 6: Track it and notice the wins
- Update a simple list of balances once a month. A table works:
| Month | Card A | Card B | Card C | Total |
|---|---|---|---|---|
| Start | ||||
| Month 1 | ||||
| Month 2 |
- Mark milestones when you reach them.
- Reward yourself in a way that doesn’t cost much, like a walk, a movie night at home or a meal you cook.
- Note how much interest you’re no longer paying. It’s a real number.
Step 7: Plan for slip-ups
You may overspend one month, miss a payment or face a big bill. That doesn’t end the plan.
- Don’t quit. Restart the next month at the same payment.
- Contact your issuer early if you can’t make a payment. The FTC advises calling before a debt collector gets involved, telling your creditors what’s going on and trying to work out a payment plan you can manage.
- Adjust the plan, not the goal. A longer timeline is better than none.
- Know the stakes of falling behind. The CFPB says that if you’re more than 60 days late, the card company can raise your interest rate.
Step 8: Get support
- A nonprofit credit counselor can review your finances, help you build a budget and, if it fits, set up a debt management plan. The FTC says a good counselor spends time with you and helps you make a plan that works. Ask about fees. See our article on credit card debt relief for your options.
- A person you trust can keep you accountable. If you share finances with a partner, have the conversation early and agree on a plan.
- Support for how you feel. If money worries leave you feeling hopeless or unable to cope, you can call or text 988, the Suicide & Crisis Lifeline. It provides free, confidential support 24 hours a day, and it covers economic worries as well as other kinds of distress. You can also talk to a doctor or a mental health professional.
A 30-day starter plan
Week 1: Look. Gather your statements, write down each balance, APR and minimum, and check your credit reports at AnnualCreditReport.com.
Week 2: Decide. Build a simple budget, pick your monthly payment and set a payoff date and first milestone.
Week 3: Automate. Set up automatic minimums, schedule your extra payment, and remove saved card numbers.
Week 4: Ask. Call your issuers and ask about a lower rate or a payment plan. Start your small cushion. Mark a monthly check-in on your calendar.
Common traps
- Avoidance. Not opening statements doesn’t stop interest. Look once a month.
- All-or-nothing thinking. One bad month isn’t failure. Restart.
- “I deserve a treat.” Plan small rewards in advance so they don’t turn into a binge.
- Comparing yourself to others. Your timeline depends on your numbers, not on anyone else’s.
- Waiting for a perfect plan. A good plan you start this week beats a perfect plan you start next year.
Frequently asked questions
How long does it take to get out of credit card debt?
It depends on your balance, your APR and how much you pay. Our payoff calculator gives you an estimate.
What’s the first step to get out of credit card debt?
Write down every balance, rate and minimum payment in one place. You can’t plan around numbers you haven’t looked at.
How do I stay motivated?
Set milestones with dates, track your progress, and use a method that gives you early wins, such as the snowball. Research suggests concentrating payments on one account helps motivation.
What if I can’t afford more than the minimum?
Talk to your creditors and to a nonprofit credit counselor. Our complete guide to credit card debt covers hardship plans, counseling and other options.
What if I slip and use the card again?
Don’t give up. Restart at your usual payment, and look at what triggered it. A small cushion can help prevent a repeat.
Where can I find support if the stress feels like too much?
You can call or text 988 for free, confidential emotional support, 24 hours a day. A doctor, a mental health professional or a nonprofit credit counselor can also help.
Sources
Information was checked in October 2026. Resources and rules change, so verify the current details.
- Winning the battle but losing the war: The psychology of debt management, Amar, Ariely, Ayal, Cryder and Rick, Journal of Marketing Research (abstract)
- Why Don’t People Manage Debt Better?, Scientific American blog
- Repayment Concentration and Consumer Motivation to Get Out of Debt, Kettle, Trudel, Blanchard and Häubl, Journal of Consumer Research, 2016
- The stress of money, with Linda Gallo, PhD, American Psychological Association
- Debt worksheet and spending tracker, Consumer Financial Protection Bureau
- A box on my credit card bill says that I will pay off the balance in three years…, Consumer Financial Protection Bureau
- Credit cards key terms, Consumer Financial Protection Bureau
- How To Get Out of Debt, Federal Trade Commission, Consumer Advice
- Report on the Economic Well-Being of U.S. Households in 2025: Savings and Investments, Federal Reserve Board, May 2026
- 988 Suicide & Crisis Lifeline, 988 Lifeline
- More Americans Have Access to Credit While Debt Growth Has Moderated (Q2 2026 Credit Industry Insights Report), TransUnion
- Consumer Credit – G.19, July 2026 release, Board of Governors of the Federal Reserve System
The numerical examples are hypothetical and calculated by us. They assume fixed rates, interest added monthly and no new purchases.